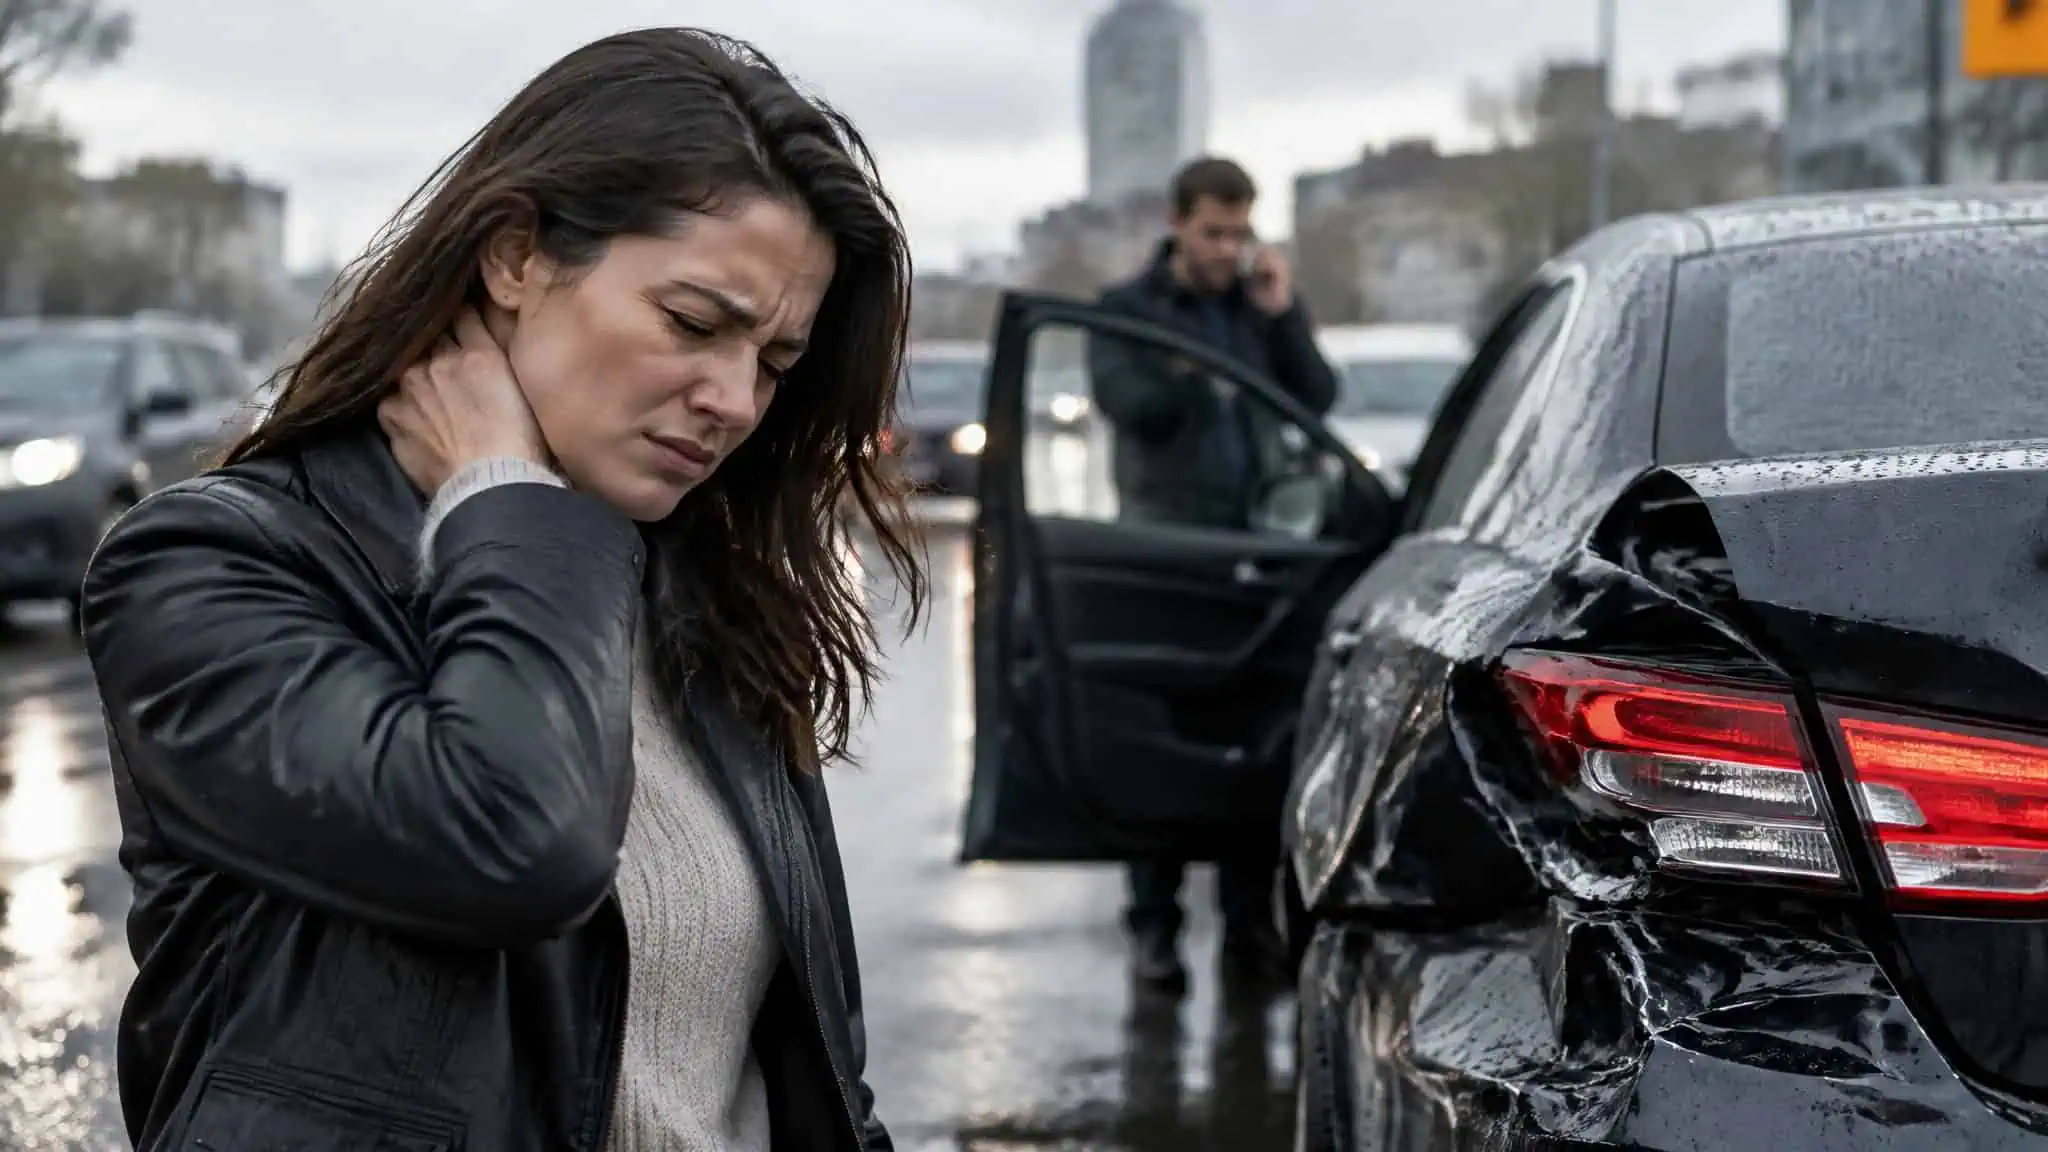
Some guy is looking at his phone instead of the road and slams into the back of your car. Your neck hurts, your car’s wrecked, and his insurance company is about to become a bigger part of your life than you’d like. That crash, and everything that follows it, is the cleanest example of a personal injury claim you’ll ever get.
A personal injury claim, at its simplest, is a demand for compensation when someone else’s negligence hurts you, and if you’ve ever been hurt because of someone else’s mistake, a personal injury lawyer can help you press that demand. The insurers evaluating it look at three things: who was at fault, what you actually lost, and whether you can prove it. That’s it. Everything else in this article is those three questions playing out with different defendants and different paperwork.
And “personal injury claim” turns out to be a loose term for three different legal animals. There’s the insurance negotiation after a car crash. There’s the case against an employer or property owner, like the UK painter who won £320,000 after his company called him a liar and then backed down weeks before trial. And there’s the mass tort, like the Navy veterans suing the manufacturers of firefighting foam over cancer-causing chemicals.
Same word, “claim.” Different defendant, different evidence, different clock.
This article follows four of them: a composite car crash from first call to settlement check, the £320,000 workplace case, the Nottingham maternity care scandal in England, and the AFFF suit Navy veterans brought over firefighting foam. If you want the short list, common claim types include car accidents, slip and fall, medical malpractice, product liability, and workplace injury.
One thing worth knowing up front, stated plainly: part of the claims process exists to keep the insurer’s payout low. Not everything, and not out of malice. But the system isn’t neutral, and knowing where the friction lives is the whole advantage.
Key Takeaways
A personal injury claim is a demand for compensation when someone else’s negligence harms you, and insurers judge it on fault, losses, and proof; a distracted driver running a red light is the textbook example.
Real outcomes vary wildly: a UK County Court awarded a painter £320,000 after his employer withdrew a “fundamental dishonesty” defense weeks before trial, and Navy veterans have extracted $10.3 billion from 3M over PFAS in firefighting foam.
Expect the friction to be structural, not personal: medical records take a week to several months to arrive, Medicare lien figures can take three months or more to finalize, and the insurer’s own software puts a dollar figure on pain and suffering, and that software tends to favor the insurer.
Table of Contents
A car accident claim, from crash to settlement
What actually happens between the crash and the check is a structured process, and here’s how it runs in a typical sequence. This walkthrough is illustrative, not a real case, but it’s how the pipeline works.
First, the insurer’s adjuster does an initial review: confirming the at-fault driver’s policy covers the accident, identifying everyone involved, and pulling the accident details. They’re already hunting for red flags, like stories from the two drivers that don’t line up or fault that’s murky.
Then comes liability. They lean on the police report, witness statements, physical evidence, and photos or video. If the crash is messy enough, an accident reconstruction expert gets involved. Sometimes more than one party shares the blame, which matters later.
Most claims never see a courtroom. Before any lawsuit, there’s an investigation, your medical treatment continues until you’re as healed as you’re going to get, and records and bills get gathered. Records alone can take a week to several months. A doctor’s office moves fast; a hospital doesn’t. Then your side sends a demand package, a letter plus records plus bills, and the other side accepts, rejects, or counters.
Insurers calculate your claim value from two buckets: economic damages plus their own formula for pain and suffering. Economic damages are your medical bills, lost wages, and out-of-pocket costs, all backed by invoices, receipts, and pay records. Pain and suffering is assigned a dollar value by the insurer’s own formulas or software, which tend to favor the insurer. That’s why the first offer is a negotiating position, not a verdict on what your claim is worth.
The adjuster isn’t a neutral referee, but it’s not chaos either. It’s a person running a structured process. Knowing the process is the edge.
Comparative negligence: the same crash, different payout
In comparative negligence states, Illinois is a well-known example, your compensation gets reduced by your percentage of fault. The arithmetic is exactly what you’d hope it is: if you’re assigned 20% of the blame, your payout drops by 20%.
So the same crash pays differently depending on the fault split. Two drivers, identical injuries, identical bills, and one walks away with thousands more than the other purely because of how fault got divided, which is why some cases end up in personal injury court at all. That’s why the fault assignment is worth disputing rather than shrugging at.
Quick test: Before accepting any fault split, ask what each percentage point costs you in dollars — then decide if it’s worth disputing.
As for your odds: they’re driven far more by liability clarity and evidence strength than by luck. A clean police report and a stack of consistent records beat wishful thinking every time.
Your medical records are the claim’s spine, and its biggest trap
The records adjusters read, ER records, physician notes, X-rays and MRIs, PT records, prove two things at once: how badly you were hurt and that the accident caused it, which is the whole reason a personal injury lawyer digs into your paper trail so carefully. Two traps live here. Wait weeks to see a doctor and the insurer argues it wasn’t that bad. Tell the officer at the scene you’re “a bit sore” and have later records say severe pain, and they’ll pounce on the gap. The record gets written in real time and can’t be rewritten, so report everything and get seen promptly.
A real claim that went the distance: the £320,000 workplace case
Here’s the answer in one case: a painter and decorator, 48 years old, fell from a step-up platform when sparks came through a hole in a wall built by Caledonian Modular Ltd, tearing his rotator cuff badly enough that an MRI about five months later confirmed the damage.
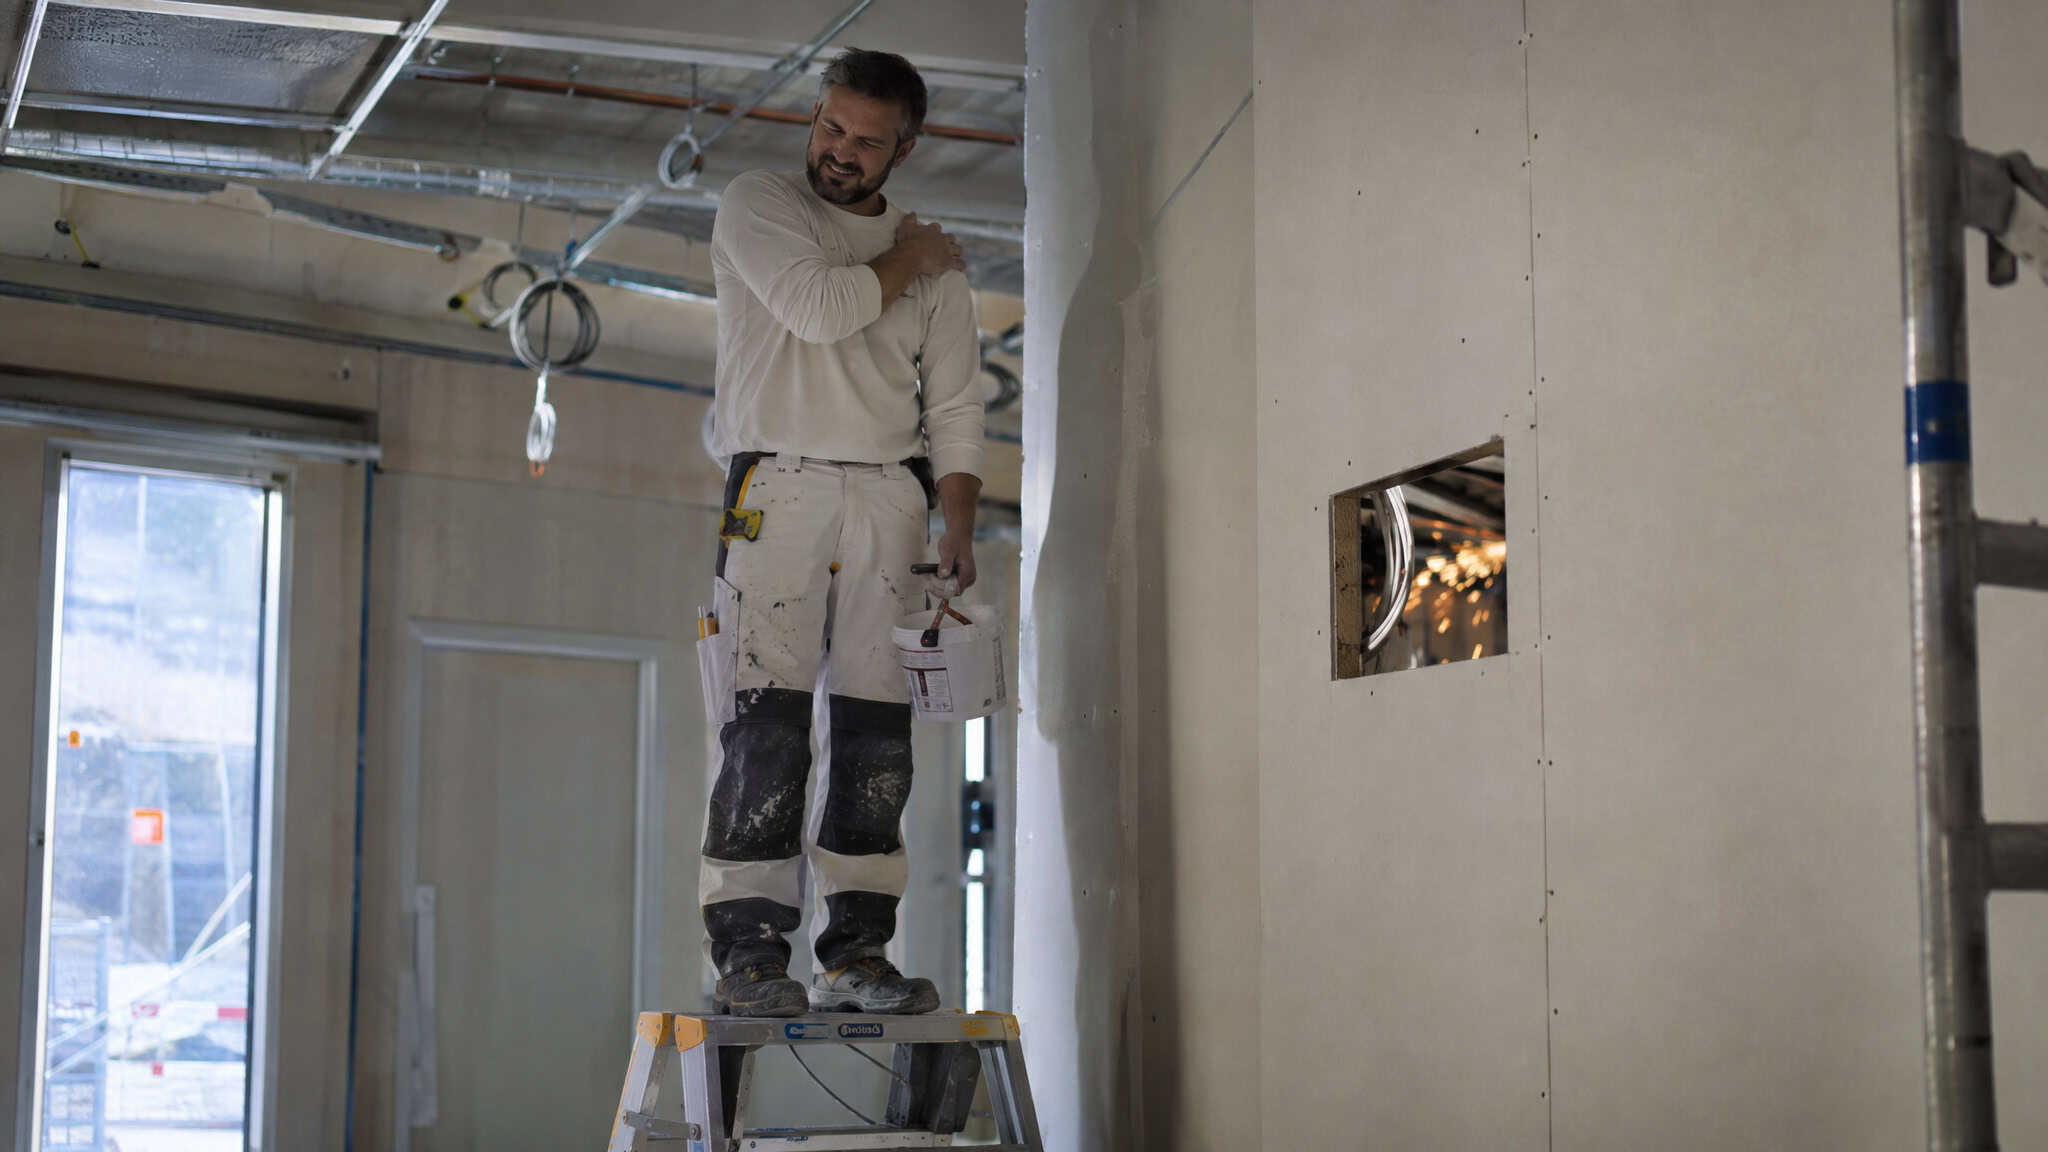
The fallout is the part that sticks. Two years unable to work. A 25-year painting career over. By his own account he went from happy-go-lucky to tense and irritable.
The strain ended his marriage. That’s what a shoulder injury actually costs when it’s bad enough.
The employer alleged “fundamental dishonesty,” then withdrew that defense weeks before trial. Read into that what you will: they saw how it was going to go. A County Court judge ruled the firm failed to protect him from an avoidable accident and awarded £320,000. The claim was handled by Hudgell Solicitors, a UK firm that’s run on no-win-no-fee since 1997.
One caveat: this is a UK case. The process lesson transfers across the Atlantic, the currency and the court system don’t.
How insurers shrink claims, and when they cross the line
Yes, insurers use specific moves to shrink personal injury claims, and you should know them before you encounter them. The big ones: endless “one more document” requests that stretch the process while your bills pile up; disputing how bad your injury actually is; blaming an old injury for your new symptoms; and questioning whether your treatment was even necessary.
The drip-request pattern works because it exploits predictable pressure. Bills are mounting, you don’t know the system, and tired people settle for less. Recognizing the pattern is the defense.
Then there’s the line, and it’s a real one. Bad faith means unreasonably denying a valid claim, failing to properly investigate, misrepresenting what your policy covers, or making offers so low they can’t be justified. Cross that line and the insurer can face a second legal claim for it. Be honest about the boundary though: ordinary delay or a single low offer isn’t automatically bad faith. But knowing that lever exists changes how you read the negotiation.
Red flag: If the insurer keeps requesting “one more document” while your bills pile up, the delay may be the strategy, not the paperwork.
What the settlement money actually is: damages math and liens
Pain and suffering damages are estimated, not measured, by the insurer’s internal formulas or software. Those tools tend to favor the insurer, and you often can’t see how they arrived at their number. That opacity is exactly why no honest article can quote you an “average settlement,” and why the first offer should be read as a starting position rather than a verdict on your claim.
Economic damages are the counterweight. Medical bills, lost wages, out-of-pocket costs: these are receipt-verified and relatively objective. Invoices, pay stubs, pharmacy receipts. There’s a number on the paper, and the paper is what gets counted. That’s the split to keep in your head: stuff with receipts, stuff without.
Here’s the flow after the insurer says yes, because the settlement figure and your check are not the same number. Medical liens come first. A lien is when a provider, a health insurer, or Medicare or Medicaid claims part of your settlement to cover the treatment costs they fronted for you. Those get repaid before you see a dime. Handled correctly, that’s fine: the liens come out of the settlement itself, so there’s no surprise bill waiting for you later.
Timelines matter here too. Getting your records together runs a week to several months. A doctor’s office is quick about it; a hospital is not. Medicare lien figures can take three months or more to finalize. So when someone tells you a case “settled,” understand that the clock between agreement and money in your account involves resolving every lien first. Expect the wait and plan around it, because nobody on the insurer’s side is going to rush it for you.
When the example changes the claim: malpractice and mass torts
Who you’re suing depends entirely on how you got hurt: malpractice puts a healthcare system across the table, and a mass tort puts a manufacturer there instead of a single insurer. Change the example and the claim changes shape with it, who the defendant is, what the evidence looks like, and how long the clock runs. The Nottingham maternity scandal shows what a healthcare-system defendant looks like when it fights: an Ockenden Review found senior managers ran an institutional cover-up, downgrading serious maternity failings for a decade to avoid external scrutiny and misleading coroners.
Medical malpractice: system failure, not one bad day
The strongest malpractice claims come from documented system failure, not a single doctor’s error. The Ockenden Review in England found that managers at Nottingham University Hospitals NHS Trust ran a decade-long cover-up, downgrading maternity failings and misleading coroners. One coroner called out 256 undeclared neonatal deaths, which stretched the investigation to four years. Half of the 60 senior executives questioned refused to answer. Some 150 doctors and midwives are now undergoing fitness-to-practise assessment, and police are investigating.
The deaths and injuries spanned 2012 to 2025. That’s the scale malpractice claims can reach when a system fails rather than an individual.
On the smaller end, Fieldfisher’s case studies show both directions: a missed pre-eclampsia escalation at St Peter’s Hospital that led to a baby’s death, and a successful birth injury claim for a boy named Freddie. Both ends of what these claims look like.
Mass tort: suing the manufacturer, not your employer
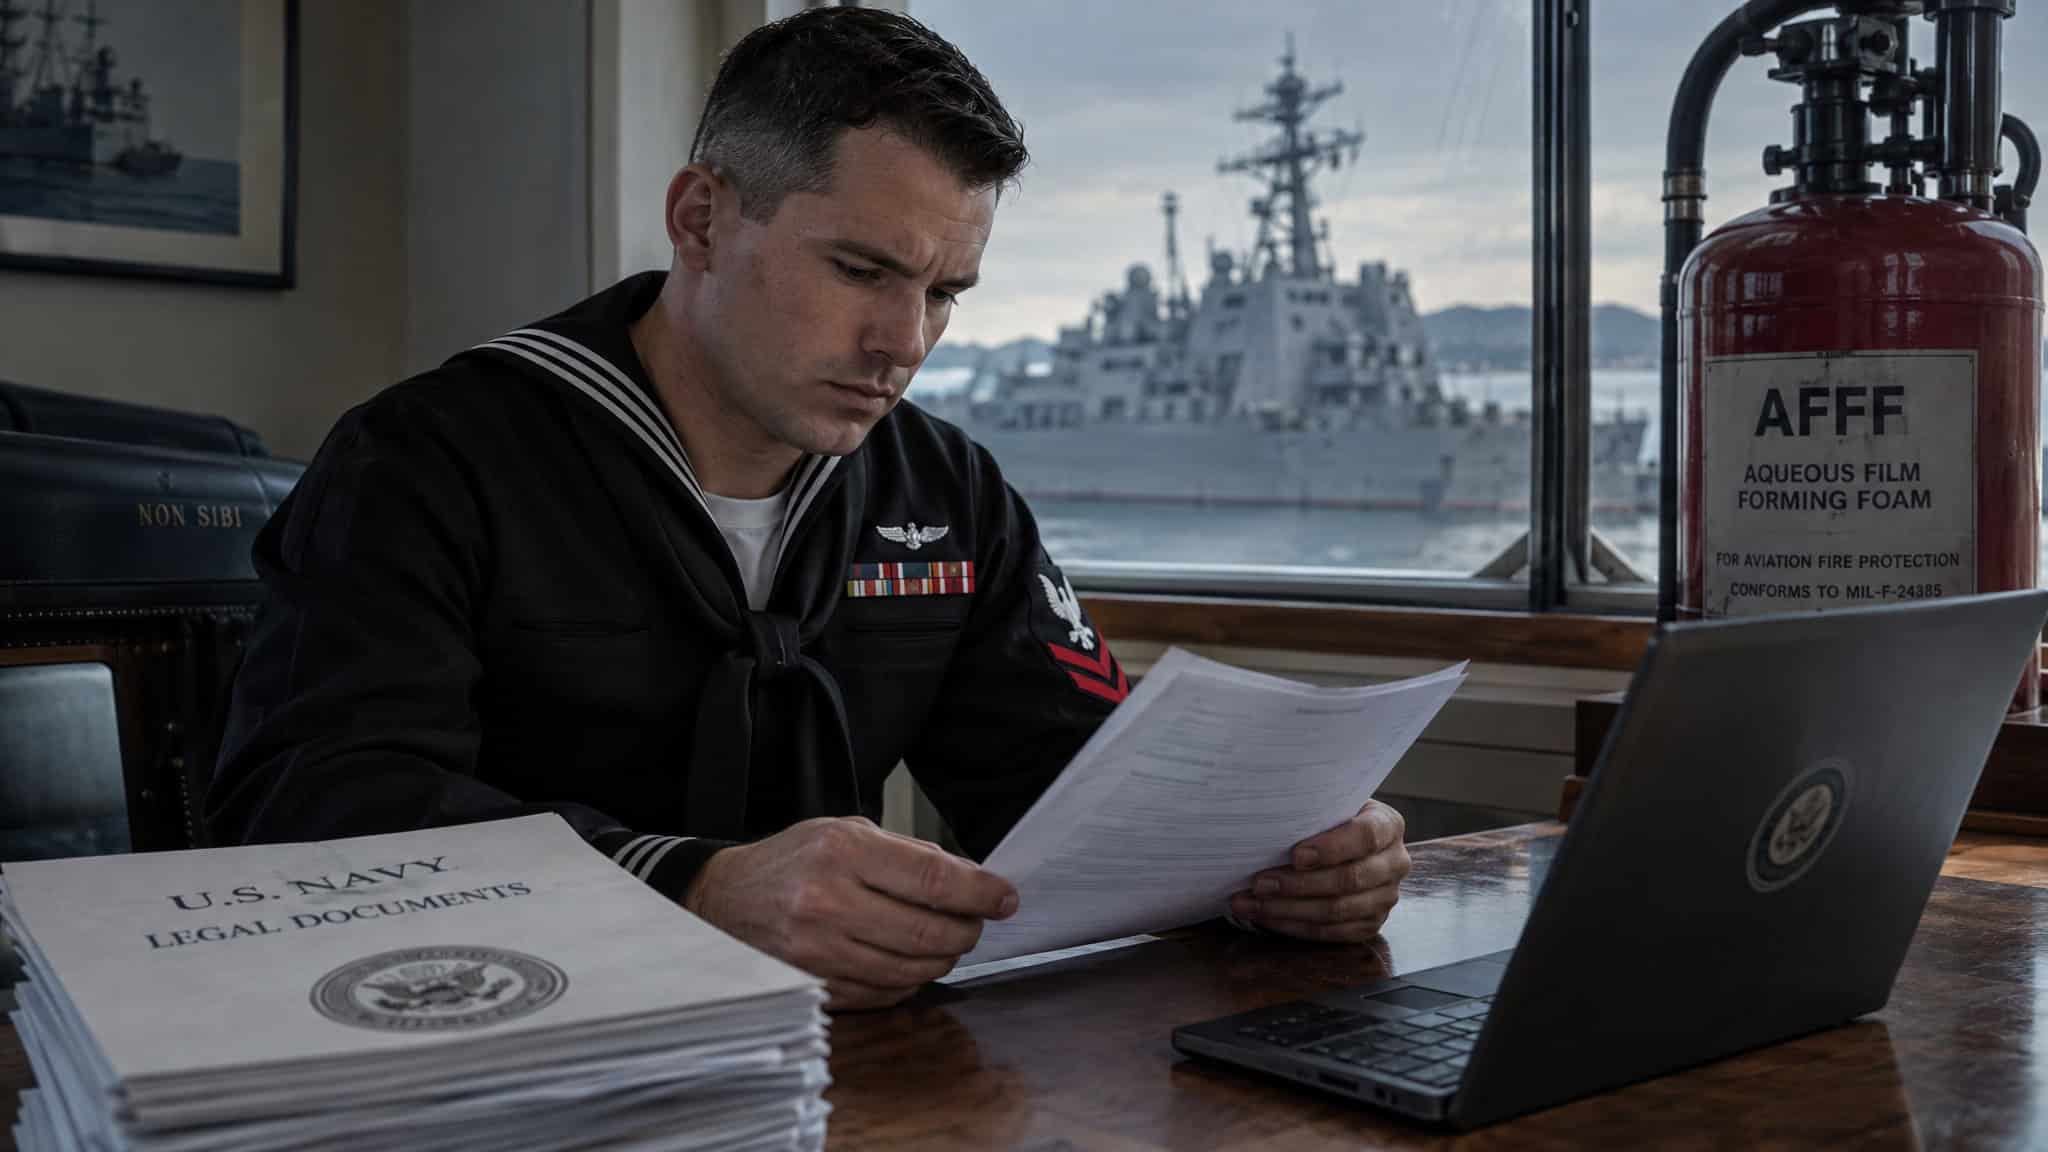
Yes, you can sue over workplace chemical exposure when the defendant is the manufacturer rather than your employer, and the Navy AFFF litigation is the running example. Navy firefighting foam contained PFAS “forever chemicals” by design. The Navy adopted it in the 1960s and required its use aboard every ship after a 1967 fire killed over 130 sailors. In 2023, a federal study tied elevated PFAS blood levels among military firefighters to increased testicular cancer risk, with links to kidney cancer and lymphoma.
Eligibility is exposure plus a diagnosed linked illness. The clock runs 2 to 3 years from diagnosis or from discovering the AFFF link, in most states. Not from exposure decades ago.
The money that has moved: 3M, $10.3 billion. DuPont, Chemours, and Corteva, $4 billion. Carrier and Kidde-Fenwal, $730 million. Tyco paid $17.5 million to Wisconsin victims. The Department of Defense set an October 2024 phase-out deadline, but shipboard use was excluded and installations can waive through October 2026.
And an August 2024 spill of roughly 1,450 gallons of the foam at Maine’s former Brunswick Naval Air Station shows this isn’t ancient history. Sickened veterans may also pursue tax-free VA disability compensation, over $3,930 a month possible depending on condition, in parallel with any lawsuit.
What it costs, when to get a lawyer, and the mistakes that sink claims
Representation typically costs nothing upfront. Contingency, or no-win-no-fee, means the lawyer gets paid only if the claim succeeds. It’s how the UK painter’s case ran, and how the AFFF mass-tort work runs. Sokolove Law is one firm working this way: free case reviews, all 50 states, over $10.5 billion recovered.
So the honest question isn’t whether you can afford a lawyer. It’s whether you can afford your own mistakes. Hold off on any recorded statement until you’ve had a chance to learn your rights, and keep the accident off social media, because adjusters check. What a lawyer actually does: reviews the claim, catches problems early, keeps documentation tight, negotiates, and can call out bad faith when the insurer crosses the line. Weigh settling alone against that, against a fee you only pay on a win, and decide accordingly.
What these examples add up to is simpler than the paperwork suggests. Same word, “claim.” Three different defendants: an insurer, an employer, a manufacturer. Three different evidence bases: your medical records, the institution’s records, your exposure history.
Three different clocks. The reusable question is the same every time: who is my defendant, and when does my clock start?
Frequently Asked Questions
What happens in a personal injury claim from accident to settlement?
The insurer’s adjuster first confirms coverage and hunts for red flags, then investigates liability using the police report, witnesses, and physical evidence. Medical treatment continues until you’ve recovered, records and bills are gathered — records alone can take a week to several months — then your side sends a demand package and the other side accepts, rejects, or counters. Once a settlement is agreed, liens from providers, health insurers, or Medicare get repaid before you see your money.

