You’ve got six tabs open and six different numbers: $15 on one site, $15,000 on another, and nothing in between that makes sense. Estate planning costs roughly $15 to $15,000+, and the cheapest plan can end up costing you the most. The same will runs $15 online or $1,500 from an attorney. The document price is the small half of the bill.
The big half is what your family pays later if the plan doesn’t hold up, and in one Massachusetts case that added up to about $68,000. First, the myth: this isn’t rich-guy stuff. If you own a house, personal property, investments, or a life insurance policy, you have an estate. No wealth threshold required.
Key Takeaways
A full attorney-drafted plan typically runs $2,000, $5,000+, a basic will $15, $1,500+, and online will-makers $0, $599, but the document fee is the smallest line item in the total cost.
Probate without a plan typically eats 3-8% of the estate’s value over 6-9 months; on a $500,000 estate that’s about $5,000 in Texas versus $26,000 in California, and Florida’s statutory fee schedule can hit $15,000 on that same estate.
Whether you need an attorney comes down to family structure, not net worth. Remarriage, a special needs dependent, a business, or a blended family all push you past what a $100 template can handle.
Table of Contents
How much does estate planning cost?
Estate planning runs from free or under $100 for DIY documents to $5,000, $15,000+ for complex attorney plans. A standard attorney-led plan typically lands at $2,000, $5,000.
| Document | Typical cost |
|---|---|
| Basic will | $15, $1,500+ (online templates start around $100, $300) |
| Power of attorney | $200, $500 each |
| Living trust or trust package | $1,000, $4,000 |
| Full attorney plan | $2,000, $5,000+ |
| Advance health care directive | $200, $1,000 |
A typical plan bundles four documents. The will says who gets your stuff. The trust handles your assets while you’re alive and after. Powers of attorney name your guy to make money and medical calls if you can’t. The advance directive puts your medical wishes on paper so nobody has to guess.
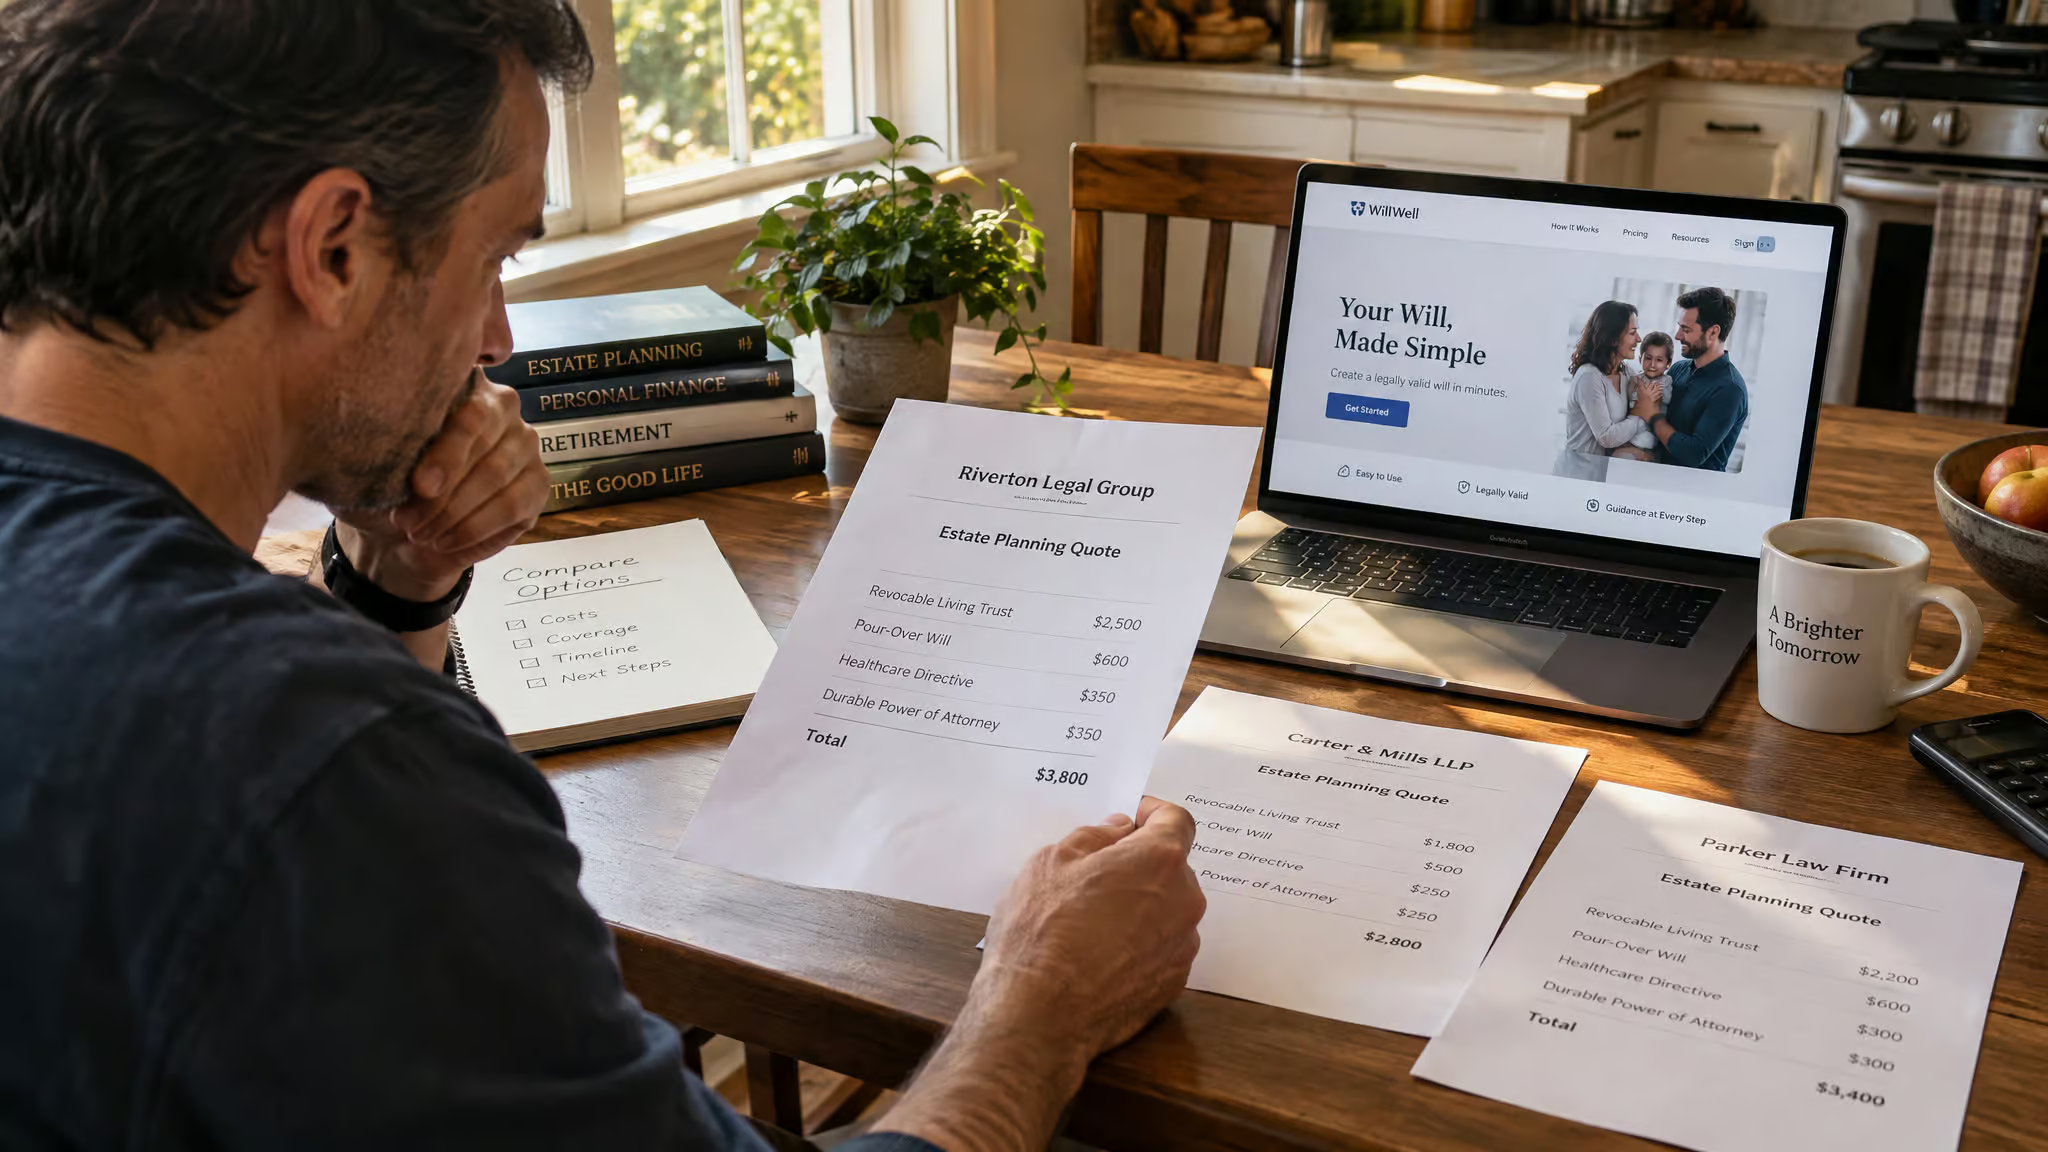
One thing the per-document pricing hides: attorneys and online platforms bundle the same four documents, so the line items are mostly packaging. What actually drives the price is which tier of bundle fits your situation, not the cost of each individual sheet. What moves the price: more assets means more attorney hours, tax-reduction goals cost more than simple distribution, trust-based plans cost more than simple wills, state rules on notarization and witnesses matter, and metro attorneys charge more than rural ones. Blended families, small businesses, messy real estate, and special needs dependents add cost too.
Not a judgment. Just more moving parts.
What an estate planning attorney charges
Making a will with a lawyer costs $300, $1,000 for the will alone in most markets. Attorney hourly rates run $162, $392 per one survey, or $200, $400 as the typical practice figure. The two ranges overlap and tell the same story: expect a few hundred dollars an hour, more in expensive markets, less for a solo guy in a small town.
Why pay that at all? Because what you’re buying isn’t paper. It’s documents that are valid, complete, and fit your situation, plus tax savings a good attorney spots that you’d miss. The real product is expensive mistakes avoided. Specialists charge more upfront but can save money long term.
There are three ways the billing works. Hourly is flexible but unpredictable: you won’t know the final bill until it arrives, and every revision costs more, so “let’s tweak the will again” adds up. It makes sense for complex or open-ended cases where nobody knows the scope upfront, the same way a day rate makes sense for a contractor job nobody can quote yet. Flat fee is one price for one job, typically a few hundred to a few thousand dollars for standard documents.
Predictable, but ask what’s included, because customizations can cost extra. Some firms, like Mark Mastrarrigo’s Florida practice, price everything flat-fee with transparent pricing, which proves the model exists. Retainers are the third option: ongoing service for updates after a new child, a relocation, a divorce, or new trust terms. It only makes sense if you expect regular changes. Otherwise pay per update and don’t sign up for the second bill.
The billing model is itself a quality signal. An attorney quoting a flat fee upfront has already scoped your estate’s complexity. Hourly billing on a “simple” will often means the scope wasn’t understood. The structure tells you which plan you’re actually buying.
Practical moves: get multiple quotes, ask directly about flat fees, and show up with your asset list and beneficiary names ready. Less back-and-forth means fewer billable hours.
Estate planning cost by state and city
The same document ranges 100x in price depending on where and how it’s made, which makes the national “average” statistically meaningless. In Florida, a basic will package runs $500, $1,500 according to Mark Mastrarrigo’s firm, and it includes the will, durable power of attorney, healthcare surrogate designation, and living will. That fits straightforward assets with no minor kids and no probate-avoidance needs, though the will still goes through probate at death. A trust-based plan runs $2,500, $5,000 individual or $4,000, $7,500 for a couple, adding the revocable living trust, pour-over will, and help funding the trust. That’s the tier for homeowners, parents of minor kids, and blended families. Complex plans with irrevocable trusts, Medicaid planning, or business succession run $5,000, $15,000+.
In Chicago, Peck Ritchey’s pricing runs $800, $1,500 for basic plans, $300, $1,000 for wills alone, $1,000, $3,000 for living trusts, $150, $500 for healthcare directives, and $3,000, $10,000+ for comprehensive plans covering tax planning and asset protection. Chicago can run above national averages. Big-city premium, no mystery.
The useful unit of comparison is your state’s attorney market plus your family structure, not a national figure. Prices vary by market and change over time, so treat every number here as a starting quote, not a final one.
How much does it cost to make a will online?
Making a will online costs free to about $300 for a basic will, with full trust packages from the major platforms at $499, $599. Here’s what you get for the money, where the upsell hides, and when the cheap option is fine.
Trust & Will runs $199 for an individual will, $299 joint, and $499/$599 for trusts. There’s a $49/year membership for ongoing access, which is the subscription catch, and $299 flat for attorney assistance, a genuine middle tier. Wills are available in all 50 states plus D.C.; trusts everywhere except Louisiana. You get a Q&A format, attorney line-by-line review, probate case managers, and printed or shipped documents.
Quicken WillMaker & Trust costs $109, $219, then $39/year for changes after year one. Read that renewal fine print twice. It’s software you own rather than a subscription, and that distinction matters for how you pay over time. It covers wills, health care directives, and living trusts, with state-tailored documents vetted by attorneys, digital storage via Everplans (your docs on someone else’s servers, normal buyer caveat), unlimited household wills, and a 30-day guarantee. Not available in Louisiana.
LegalZoom’s Estate Plan Bundle is $149 solo, $249 for couples, with plans running $0/$249/$299 plus state filing fees. Watch the “plus.”
FreeWill is actually free, funded by hundreds of nonprofits without selling your data, which is how “free” makes sense. The will takes about 20 minutes in all 50 states plus D.C., though the signing ritual still takes real effort. Trusts are limited to California.
Ethos, better known for life insurance, charges $149 for a will or $449 for the full package, and the will is free if you buy a life insurance policy. The catch is right there; you can judge the trade. Not available in Alaska, Louisiana, South Dakota, or Washington.
Rocket Lawyer works differently: $39.99/month or $19.99/month for the lower tier, with attorney chat responses within one business day. It’s attorney access, not just documents. The free 7-day trial is useful for a one-off will if you cancel in time. Say the quiet part out loud.
CNBC’s roundup sorts the field: Trust & Will for families, Quicken for advance medical directives, LegalZoom for comprehensive planning, FreeWill as the free option, Ethos paired with life insurance, Rocket Lawyer for attorney access.
DIY wins stated honestly: low upfront cost, done from the couch, and fine for simple situations like one property, limited accounts, and one or two beneficiaries. Online services also make sense for anyone starting from zero, with no will in place, because something beats nothing. The tradeoff: the $100, $300 savings is a bet that your state’s execution formalities and your asset structure match the template.
When a cheap online will fails in court
A cheap online will runs into trouble when it doesn’t meet your state’s execution requirements. The document itself can be perfectly legal; the catch is the requirements, not the product. Most states want it signed and witnessed by two people who aren’t getting anything from the will. Some states allow e-signatures, but most still want ink on paper, just over a dozen accept fully digital wills, and some require notarization. Check yours before assuming the PDF is done.
The concrete failure mode is Florida, which requires two witnesses plus notarization for a self-proving will under Fla. Stat. § 732.502. Generic templates can blow those requirements or ignore homestead restrictions, because the template doesn’t know you live in Florida. Estate attorneys report the same pattern with DIY documents: the family discovers at probate that witnessing or notarization wasn’t met, or a state rule the template didn’t address forces a partial intestate outcome.
A will that doesn’t meet the formalities is invalid, and DIY documents tend to break down at precisely the moment they’re needed. A $100 tool can also choke on complex situations or state-specific laws; Illinois is the sourced example, with missing witness signatures and tax clauses as the common gaps. Fixing a broken plan costs far more than the template saved. As Massachusetts estate attorney Patrick Kelleher puts it, a $500 will gets about $500 worth of protection.
Quick test: Before you file a DIY will away, confirm your state’s witness, notarization, and signing rules are actually met.
DIY will vs. attorney: which one fits your family
Yes, an online will works when the estate is simple: one property, limited accounts, one or two beneficiaries. No, hire an attorney when the trigger list applies. The decisive point is that complexity is structural, not financial. A modest estate with a blended family or a special needs dependent needs costlier tailored provisions than a wealthy but simple estate.
Michael Fiffik, a LegalShield provider attorney, makes the point directly: your family situation dictates whether you’ve got a complicated estate, and “It’s a whole lot less about how much money you have.” Jill Schlesinger of CBS News keeps a similar checklist: second marriage, family estrangement, a special needs family member, business or partnership ownership, substantial wealth. All attorney territory. Treat it as a way to spot when you’re out of your depth, not a quiz.
Before requesting a quote, run the self-assessment any consultation will cover anyway: what you own and how it’s titled, your marriage and any prior ones, minor children or special needs dependents, business ownership, whether probate avoidance matters to you, and who you want to get what.
And here’s a pattern that shows up again and again among will shoppers: they price a $500 online will, then discover a life event, a remarriage, a business, a special needs dependent, that changes the answer.
The hidden back-end costs: probate, taxes, and long-term care
Probate without an estate plan typically consumes 3-8% of the estate’s value, takes 6-9 months, and hits about 2.6 million estates a year. Probate is the legal process of sorting out a dead person’s estate: court, paperwork, waiting. On a $500,000 estate, that runs about $5,000 in Texas to $26,000 in California over 12-18 months.
Patrick Kelleher’s point: the fee you pay now is small next to what the estate gets charged after you’re gone. Four things stack up: probate court and attorney fees, estate taxes, beneficiary turmoil (lawsuits, divorces, in-laws turning into outlaws, assets leaving the bloodline), and long-term care if you’re incapacitated.
Florida sets the price list: statutory probate fees under Fla. Stat. § 733.6171 run 3% of the first $1 million and 2.5% of the next $1-3 million, so a $500,000 estate can hit $15,000 in statutory attorney fees alone, plus filing and personal representative fees. Put that next to a ~$3,000 trust plan that avoids probate entirely and the numbers talk, though cheap Texas probate shows the trust math stays state-dependent.
Massachusetts has no statutory fee cap, so a $50,000 probate legal bill on a $1 million estate with a simple $500 will isn’t uncommon, and being one dollar over the state’s estate tax threshold means about $18,000 owed. Roughly $68,000 combined. Kelleher also describes one case that ran 8 years with 20-some beneficiaries who no longer speak; that’s an outlier against the 6-9 month average, not the norm.
Long-term care is the biggest unpriced line: 70% of people 70 and over will need some type of care, and the average nursing home stay runs about three years at $15,000/month in Kelleher’s area, up to $18,000 elsewhere and $500, $600/day for skilled nursing. A 36-month stay is roughly $540,000 private pay. An irrevocable Medicaid asset protection trust may protect the home, and a comprehensive plan from a qualified attorney runs $5,000, $10,000 depending on region, assets, and protections. Against those back-end numbers, the front-end fee starts looking small.
On taxes: the federal estate tax only applied above roughly $13.61 million under the 2024 exemption, and Florida has no state estate or inheritance tax. Most families will never see this tax.
Will vs. living trust: what the extra cost buys
A will goes through probate and becomes public record, meaning anyone can read it. A trust costs more upfront, $1,000, $4,000, but skips probate, stays private, and is harder to contest. The trade is more setup work now.
The trust premium pays for the work, not the document. A trust-based plan adds the revocable living trust, a pour-over will as the backup, and trust funding guidance, which means retitling your assets. A trust that isn’t funded protects nothing, so ask any trust seller how funding gets handled.
Some stuff skips the will entirely: 401(k)s, bank accounts, life insurance with named beneficiaries, and jointly titled accounts all pass outside it.
The adoption data runs both directions. Where probate hurts, people plan around it: about 72% of LegalZoom customers in California and 71% in Nevada chose trusts, while plain wills dominate in streamlined-probate Pennsylvania and Texas. The same $3,000 trust is a bargain in California and possibly unnecessary in Texas. Trust adoption also rose fastest in low-cost probate states: more than 23 percentage points in Kentucky and Iowa, more than 21 in Arkansas, from the first half of 2025 to the first half of 2026. LegalZoom points to privacy, flexibility, and preparing for expected inheritances as motives beyond probate avoidance.
Privacy and flexibility now drive trust adoption as much as probate math. As www.ledlawyers.com notes, probate can be time-consuming, costly, and subject to court oversight, which is why many people turn to trusts and other strategies to avoid or minimize it.
For the majority case, the verdict holds: a living trust pays off for most homeowners and parents of minor kids. It costs more upfront, but means less drama later and assets that move faster.
What happens if you die without a will or estate plan
Die without a plan and you don’t avoid the cost. You default into state intestacy law, what Kelleher calls the “government plan,” where the state decides who gets your stuff and can skip people you’d want included. Your girlfriend, your buddy, your stepkid. The state doesn’t know them. The estate still goes through probate and becomes public record, disputes among family members can develop, and taxes can take a bite out of an unplanned estate, though with the federal exemption at roughly $13.61 million under the 2024 rules, that last one is rare for most readers.
These no-plan costs can dwarf the price of a decent plan: the Massachusetts case above stacked roughly $68,000 against a $500 will. Everyone has an estate plan: the one they write or the one their state legislature wrote for them.
Larry King died without a comprehensive estate plan, leaving assets exposed to probate, estate tax, creditors and predators, and long-term care costs.
Two separate problems here: how much money is moving, and why so few people have planned for it. $84, $124 trillion is expected to pass between generations over the next two decades. Only 24% of Americans had a will in 2025 per Caring.com. Trust & Will puts it at 56% of U.S. adults with no estate planning documents, and note that source sells the product. Kelleher’s number is about six in ten without a will.
And 43% of people without a plan just haven’t gotten around to it.
How much does a trust cost to maintain?
There’s no standard annual fee for maintaining a trust, at least not one anyone has reliably documented. What the record does show is a rhythm: reviews every few years and fees for updates. Review the plan every 3-5 years or after major life changes: marriage, a kid, divorce, a move. The trigger list matters more than the calendar. Wills get amended with a codicil; trusts get amended or restated, so updates are normal, not a sign you did something wrong. Attorneys charge retainers or periodic review fees for continuing support like trust updates.
One more check: out-of-state documents may technically be valid but can miss state-specific rules like Florida’s homestead restrictions or the Lady Bird deed. Moved recently? Get it checked by a local attorney. Estate planning is a subscription, not a purchase. Plan for a 3-5 year review cycle instead of treating the plan as done.
How to lower the cost of estate planning on a budget
Compare attorney quotes, ask about flat fees, and show up with your asset and beneficiary information ready. The middle tier almost nobody prices out is hybrid DIY plus paid attorney review: Trust & Will’s $299 flat attorney assistance and Rocket Lawyer’s attorney-access subscription are the concrete versions. A staged approach works the same way: draft your will and beneficiaries with a free tool now, then pay an attorney only for the trust or tax pieces once your estate actually gets complicated. At the $0 end, the ABA keeps a free legal help list and FreeWill’s nonprofit-funded will costs nothing. And if you’re part of the 43% who just haven’t gotten around to it, only 24% of Americans had a will in 2025, per Caring.com, the cheapest plan is the one you actually finish.
Are estate planners worth it?
For most readers, yes, and the worth-it question resolves against the back-end math, not the front-end quote. A $3,000 trust against a $15,000 Florida probate bill answers it. So does a $5,000, $10,000 comprehensive plan against the $68,000 Massachusetts example, though treat that figure as one sourced example, not an average.
Josh Hodges of the National Council on Aging frames the value side: estate planning provides a clear roadmap for your family and reassurance for you, a powerful way to make sure the people you love are taken care of in the years to come. Stripped of the sentiment, the product is a smooth handoff with no courtroom and no guessing.
So match the plan tier to your family structure using the trigger checklist. Verify your state’s execution requirements on any DIY document before you file it away. Then schedule the 3-5 year review, because the document fee was never the real cost anyway.
Frequently Asked Questions
Are estate planners worth it?
For most people, yes — the math resolves on the back end, not the front-end quote. A $3,000 trust plan against a $15,000 Florida statutory probate fee on a $500,000 estate answers itself, and a $5,000–$10,000 comprehensive plan looks cheap next to a documented Massachusetts case that cost about $68,000. The product you’re buying is expensive mistakes avoided, not paper.
What is the biggest mistake with wills?
The most common failure is skipping your state’s execution formalities — most states require two disinterested witnesses, some require notarization, and only about a dozen accept fully digital wills. Florida, for example, requires two witnesses plus notarization for a self-proving will, and generic templates can blow those requirements or miss state rules like homestead restrictions. A will that fails the formalities is invalid, and families often discover this at probate.
What does an attorney charge for estate planning?
A will alone runs $300–$1,000 in most markets, and a full attorney-drafted plan typically lands at $2,000–$5,000+. Hourly rates run roughly $200–$400, with flat fees common for standard documents and retainers for ongoing updates. Expect higher prices in big metros — Chicago comprehensive plans run $3,000–$10,000+.
How much does estate planning cost?
Anywhere from free to $15,000+: online will-makers run $0–$599, a basic attorney-drafted will $300–$1,500, and a full attorney plan $2,000–$5,000+, with complex plans hitting $15,000+. The document fee is the smallest line item — the bigger cost is what your family pays later in probate, which typically eats 3–8% of the estate’s value over 6–9 months if you don’t plan.
How much does it cost to make a will online?
Free to about $300 for a basic will, with trust packages from major platforms at $499–$599. FreeWill is genuinely free (nonprofit-funded, all 50 states plus D.C.), Trust & Will runs $199 for an individual will, Quicken WillMaker is $109–$219 as software you own, and LegalZoom’s bundle is $149 solo. Watch the subscription fine print — annual memberships and renewal fees are where the upsell hides.
How much does a trust cost to maintain?
There’s no standard annual fee; the documented pattern is periodic review fees or attorney retainers for updates. The practical rhythm is a review every 3–5 years or after major life events, with wills amended by codicil and trusts amended or restated. If you’ve moved states, get the plan checked locally — out-of-state documents can be technically valid but miss state-specific rules like Florida’s homestead restrictions.
When does a cheap online will fail to hold up in court?
When it doesn’t meet your state’s execution requirements — witness signatures, notarization, or signing rules the template didn’t account for. The document itself can be perfectly legal; the failure is the formalities, and attorneys report families discovering at probate that witnessing wasn’t met or a state rule forced a partial intestate outcome. A $100 tool also chokes on complex situations like blended families, businesses, or special needs dependents.
DIY will vs estate planning attorney for a blended family or small business — which do I need?
Hire an attorney. Complexity is structural, not financial: remarriage, a business or partnership, a special needs dependent, or a blended family all push you past what a template can handle, regardless of your net worth. As one provider attorney puts it, it’s a whole lot less about how much money you have — your family situation dictates whether the estate is complicated.
Will vs. living trust: what does the extra cost actually buy?
A trust costs $1,000–$4,000 upfront versus a will, but skips probate, stays private, and is harder to contest. The premium pays for the work, not the document: a revocable living trust, a pour-over will as backup, and funding guidance — retitling your assets, since an unfunded trust protects nothing. It pays off for most homeowners and parents of minor kids, though in low-cost probate states like Texas a plain will may be enough.