Nobody buys a house expecting to get ambushed by a $16,000 roof. But that’s what happens to a lot of guys, because the only number anyone repeats about home maintenance — save 1% of your home’s value every year, is a floor, not a ceiling. One way to free up cash for those surprise repairs is to switch to a no deposit electricity plan, which lets you power your home without a hefty upfront fee to the provider.
So how much should you budget for home maintenance? No single number works for every house. But the data gives you something better than a guess: a real range, a few simple ways to calculate where you fall in it, and a clear picture of where the money goes.
Key Takeaways
The 1% rule is a 1%–4% range: a $200,000 house needs $2,000–$8,000 a year, and a $350,000 house needs $3,500–$14,000.
Homeowners think they’ll spend $70,000 on lifetime maintenance; the actual average is $339,000, or over $400,000 with emergency repairs.
The three biggest budget-busters — roof replacement at $5,800–$16,000+, HVAC replacement at $5,000–$16,000, and burst pipes averaging $4,284 — can hit within a few years of each other.
Table of Contents
The 1% Rule Is a Floor, Not a Ceiling
The rule you’ve heard is real, but it’s not the rule you think it is. Most sources put the 1% rule at 1% to 4% of your home’s value per year. Specialists who focus on routine maintenance — the predictable stuff, not the disasters, often narrow it to 1% to 2% of the purchase price.
Run the math and the range gets wide fast. A $200,000 home means $2,000 to $8,000 a year. A $350,000 home means $3,500 to $14,000. That’s a $10,000 spread, and where you land in it depends entirely on the house you own.
The guys who get hurt treat 1% as the ceiling. The guys who plan treat it as the floor. The trick is picking the calculation method that matches your house — and there are three worth knowing.
One more thing to factor in: inflation. Construction materials and labor costs rise every year, so the 1–4% range should be adjusted upward annually. The Bureau of Labor Statistics producer price index for construction shows steady increases, meaning a $200,000 house today will need more than $2,000 in maintenance a decade from now. Recalculate your target each January to keep pace.
Three Ways to Calculate Your Savings Target
None of these methods is wrong. They answer different questions, and one of them is weaker than the other two.
Percentage Rule: Best for Most Homes, With an Adjustment
Save 1% to 4% of your home’s value every year. It’s the most flexible and the most commonly cited method, and it scales with your market value — if the house appreciates, your target grows with it.
The weakness is the range itself. “Somewhere between 1% and 4%” isn’t a budget; it’s a shrug. You need to know where you fall. Newer house in a stable market?
You’re near the low end. Older house, or one in a high-cost area? Plan on the top half.
Square Footage Rule: Quick Math, Real Blind Spots
The square footage rule is exactly what it sounds like: $1 per square foot per year. A 3,000-square-foot house means $3,000 a year. A 4,000-square-foot house means $4,000. No percentages, no market value, no fuss.
HomeGuide says it’s less effective than the percentage method, and that’s fair: it only factors in size. It ignores the age of the house, the condition of the systems, and what the property is actually worth. It has one advantage, though. During market inflation, when home values climb and a percentage of a stale value falls behind, the square footage number keeps up.
Use it for quick mental math on newer construction in a stable market. For an older home or a high-value property, it’ll come up short every time.
Set Dollar Amount Rule: The Most Realistic for Tight Budgets
Pick a number you can actually save each month, regardless of what the house is worth. Maybe it’s $50. Maybe it’s $200. Automate a transfer so the money moves on payday and you don’t have to think about it.
This is the most flexible method and the most honest one for cash-strapped owners. It won’t fund a roof in a year, but something is better than nothing — and you can always bump the number up later.
Whichever method you pick, the gap between what you’re saving and what you’ll need is probably bigger than you think.
What Homeowners Actually Spend
A Synchrony study found that homeowners expect to spend about $70,000 on maintenance over a lifetime of ownership. The actual average is $339,000. Add emergency repairs and it’s over $400,000.
To be clear, that’s an average spread across roughly five decades of owning a home, not a prediction for every house. But the gap between expectation and reality is enormous, and it explains why so many guys hit their first big repair with an empty fund.
Zillow and Thumbtack’s 2025 data makes the annual picture just as stark. Hidden homeownership costs average $15,979 a year nationwide: $10,946 for maintenance, $2,003 for insurance, and $3,030 for property taxes. That’s $1,325 a month on top of your mortgage.
It’s also getting tighter. Hidden costs rose 4.7% in a year while incomes rose 3.8%.
Angi’s 2024 State of Home Spending report shows how much this fluctuates. Average maintenance spending dropped to $1,750, and emergency spending fell to $978 — down from $2,458 and $1,667 the year before. Maybe more people are doing preventative work. Maybe they’re just deferring. The next stat suggests the latter.
Ninety percent of homeowners say they have a repair need right now, and nearly half of them haven’t addressed it because of cost. So if you’re staring at a list of stuff you’ve been putting off, that’s not a personal failing. It’s the normal state of American homeownership.
The pattern I keep seeing: a guy adds up the mortgage, taxes, and insurance, feels fine, then discovers the roof, furnace, and water heater all have expiration dates he never checked. He tries budgeting for upkeep, the 20-year-old roof starts leaking the same year the Phoenix HVAC quits, and the fund is gone with one invoice.
Major Repair Costs: What to Really Expect
Three things will damage your budget: the roof, the HVAC system, and the plumbing.
A roof replacement runs $5,800 to $16,000, and the average bill for a leaky or damaged roof lands at $11,373. An HVAC replacement runs $5,000 to $11,000 without new ductwork, or $7,000 to $16,000 with it; when the system actually fails, the average replacement is $8,219. Burst or leaking pipes average $4,284.
Add those three together and you’re at roughly $24,000 before you touch anything else. The rest of the usual suspects, for reference:
- Furnace replacement: $2,000–$5,400
- Central AC replacement: $3,900–$8,000+
- Water heater: $800–$1,800+
- Windows: $230–$1,500 each, or $4,500–$22,500 for a 10- to 15-window house
- Deck replacement: $25–$50 per square foot
- Garage door opener: $200–$500+
- Appliances: $400–$1,000+ for standard models, several thousand more for high-end ones
The problem isn’t the individual bills — it’s the timing. When a house hits 15 to 20 years old, several of these can land within a couple years of each other. That’s the scenario that wipes out a modest savings fund in one season.
Bottom line: Three big-ticket items — roof, HVAC, and plumbing — can total roughly $24,000, and they often cluster around the same years.
The Ongoing Costs Everyone Forgets
Major replacements get the headlines. The steady drain is what eats a budget, because most guys save for the big stuff and forget the house bills them monthly just for existing—which is exactly why you should include a 5–10% buffer for surprise costs.
- Landscaping: $100–$200/month
- Lawn care: $40–$80/hour; a one-time mow runs $30–$85; full service runs $100–$400/month
- Interior painting: $1–$6 per square foot; $300–$1,200 per room; $2,900–$8,800 for the whole house
- Exterior painting: $3–$6 per square foot; $2,600–$5,700 for a full exterior
- HVAC tune-ups and repairs: $75–$150 per visit; tune-ups run $70–$200
- Appliance repairs: $100–$400 on average
- Roof shingle repair: $350–$1,500
- Emergency plumbing: $120–$300/hour on nights and weekends; $225–$450+ on holidays
- Furnace cleaning: $70–$100 basic; $150–$300 when it needs more work
Here’s the trap: a guy budgets $3,000 for “maintenance,” spends $1,200 on landscaping and $500 on a furnace tune-up, and is down to $1,300 before anything actually breaks. These aren’t optional. If you’ve got an HOA, skipping the lawn isn’t really a choice, and skipping the furnace tune-up just moves the cost to a worse day.
How Long Your Major Components Will Last
How long things last is the best planning tool you have. A 20-year-old roof means a replacement coming somewhere in the next 0 to 10 years, at $5,800 to $16,000. A 5-year-old furnace gives you a decade to save $2,000 to $5,400. That’s the difference between planning and panicking.
Here are the ranges worth knowing:
- Roof, asphalt shingles: 20–30 years; metal roofs run about 50
- Furnace: 15–25 years; some go 30, but expect issues after 15
- Central AC: 7–20 years
- Water heater, tank: 6–12 years
- Garage door opener: 10–15 years
- Windows, wood: 20–30 years
- Washing machine: 10–11 years
- Dryer: about 13 years
- Refrigerator: 13–14 years
- Range: 14–17 years
- Dishwasher: 9–10 years
Prioritize by urgency. If the water heater is on its last legs and the roof has a few years left, fix the water heater first — it’s the bill that’s actually coming. And treat these as ranges, not deadlines. A furnace might last 25 years in a mild climate and 15 in a brutal one. They’re planning tools, not prophecies.
Insurance and Property Taxes Eat Your Maintenance Budget
Insurance isn’t a maintenance cost, so don’t put it in your maintenance fund. But it competes directly with that fund, and right now it’s winning.
Homeowners insurance premiums are up 48% nationally in five years. Zillow senior economist Kara Ng says insurance premiums are climbing at nearly double the rate of homeowner incomes. That’s money that would have gone into the repair fund, now going to the insurance company instead.
Some cities are getting crushed. Miami premiums average $4,607 a year, up 72% in five years. New Orleans is up 79%. Sacramento, 59%.
Atlanta, 58%. Jacksonville, Tampa, and Orlando all jumped 68% to 72%, and Riverside, California, is up 56%.
The spike shows up in the broader hidden costs data too. New York City homeowners face $24,381 a year in hidden costs — maintenance, insurance, and taxes combined. San Francisco runs $22,781, Boston $21,320, Seattle $21,175, Miami $19,959, Los Angeles $19,321. Property taxes alone average $3,030 a year nationwide.
For a guy in Miami, the $4,607 insurance bill means $4,607 he can’t spend on roof repairs or a new furnace. That’s the squeeze, and it’s why location plays such a big role in this whole calculation.
Why Costs Vary: Home Age, Location, and Maintenance History
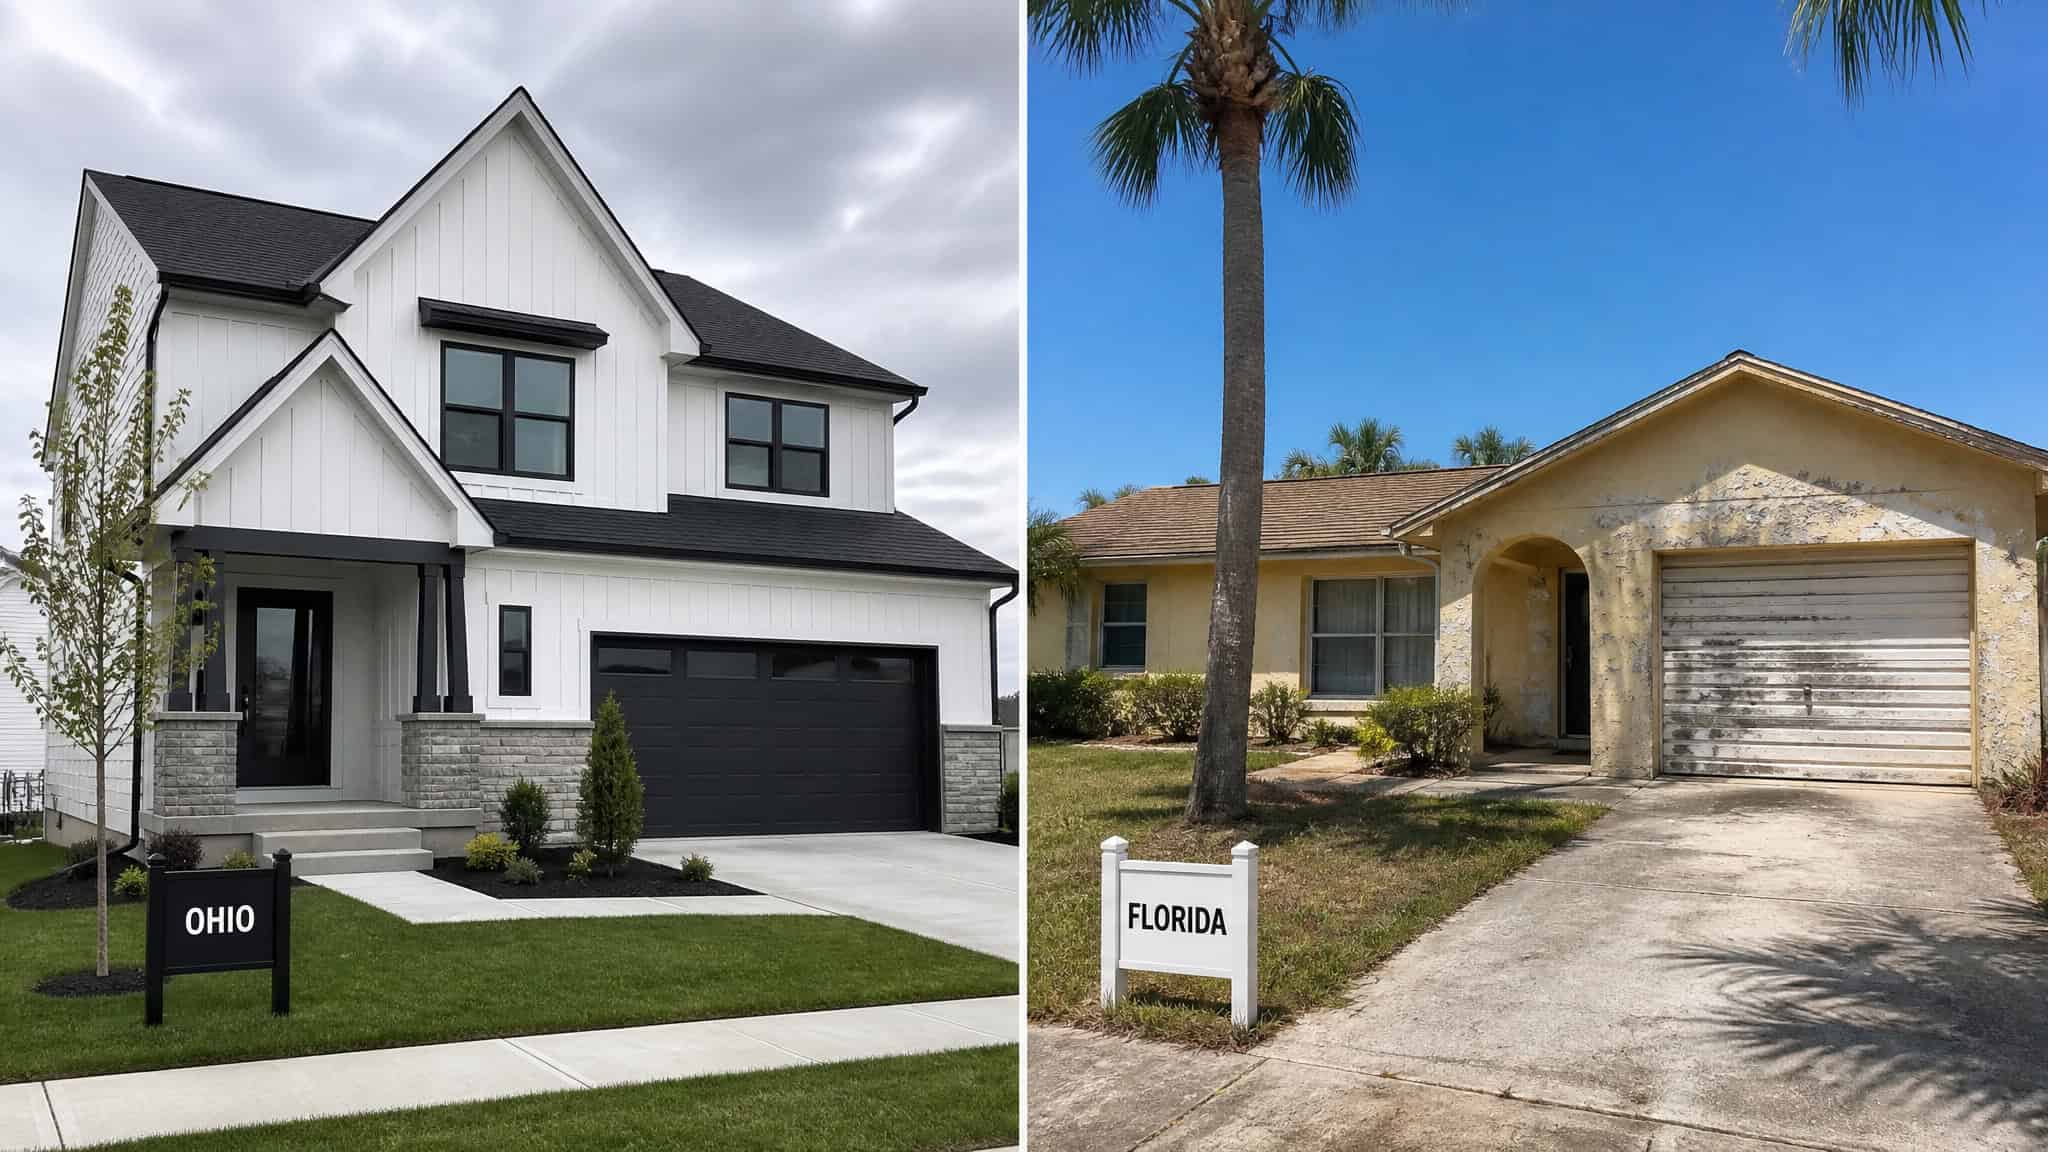
Here’s the comparison that makes it concrete: a 1,500-square-foot new build in Ohio can reasonably use the 1% rule. A 1,500-square-foot, 50-year-old house in Florida needs 2% to 4%. Same size, completely different reality.
- Home age is the big one. Older homes need 2–4% because systems wear out and replacements come more often. New construction can often get away with 1%, especially while everything is still under warranty.
- Location and climate. Coastal and disaster-prone areas face higher insurance and more wear on the structure. The same house costs more to keep in Florida than in Ohio.
- Maintenance history. Deferred repairs compound. A small leak ignored becomes major water damage, and if the previous owner skipped the upkeep, you’re the one who pays for it.
- Material quality. Spending more upfront on quality materials cuts long-term costs. Cheap windows and siding are the expensive version.
- Local regulations. Some costs are mandatory even when nothing’s broken — smoke detectors, for example, need replacing after about 10 years.
- Ownership matters. A 2021 Urban Studies study in Rochester, New York, found the worst code violations in absentee-owned properties. People who live in their homes take better care of them. If you’re renting a property out, plan for maintenance to run about 25% of your overall expenses.
Also worth knowing: plumbers charge $25 to $200 an hour depending on the job and location. Rates like that are why a “small” repair can still sting if you’re not ready for it.
Climate change is quietly rewriting the math behind the 1–4% rule. More frequent storms, intense heat waves, and shifting freeze-thaw cycles accelerate wear on roofs, HVAC systems, and foundations—pushing maintenance costs toward the upper end of that range. A roof that might have lasted 25 years in a stable climate can fail sooner under hail or extreme sun, and an AC unit working overtime in a heat wave burns out faster. If you’re in a region seeing more extreme weather, plan for the 4% end, not the 1% floor.
How to Build Your Maintenance Fund
The calculation only works if the money exists when you need it. Here’s the setup that makes that happen, and keep upgrades out of this account — new countertops aren’t maintenance.
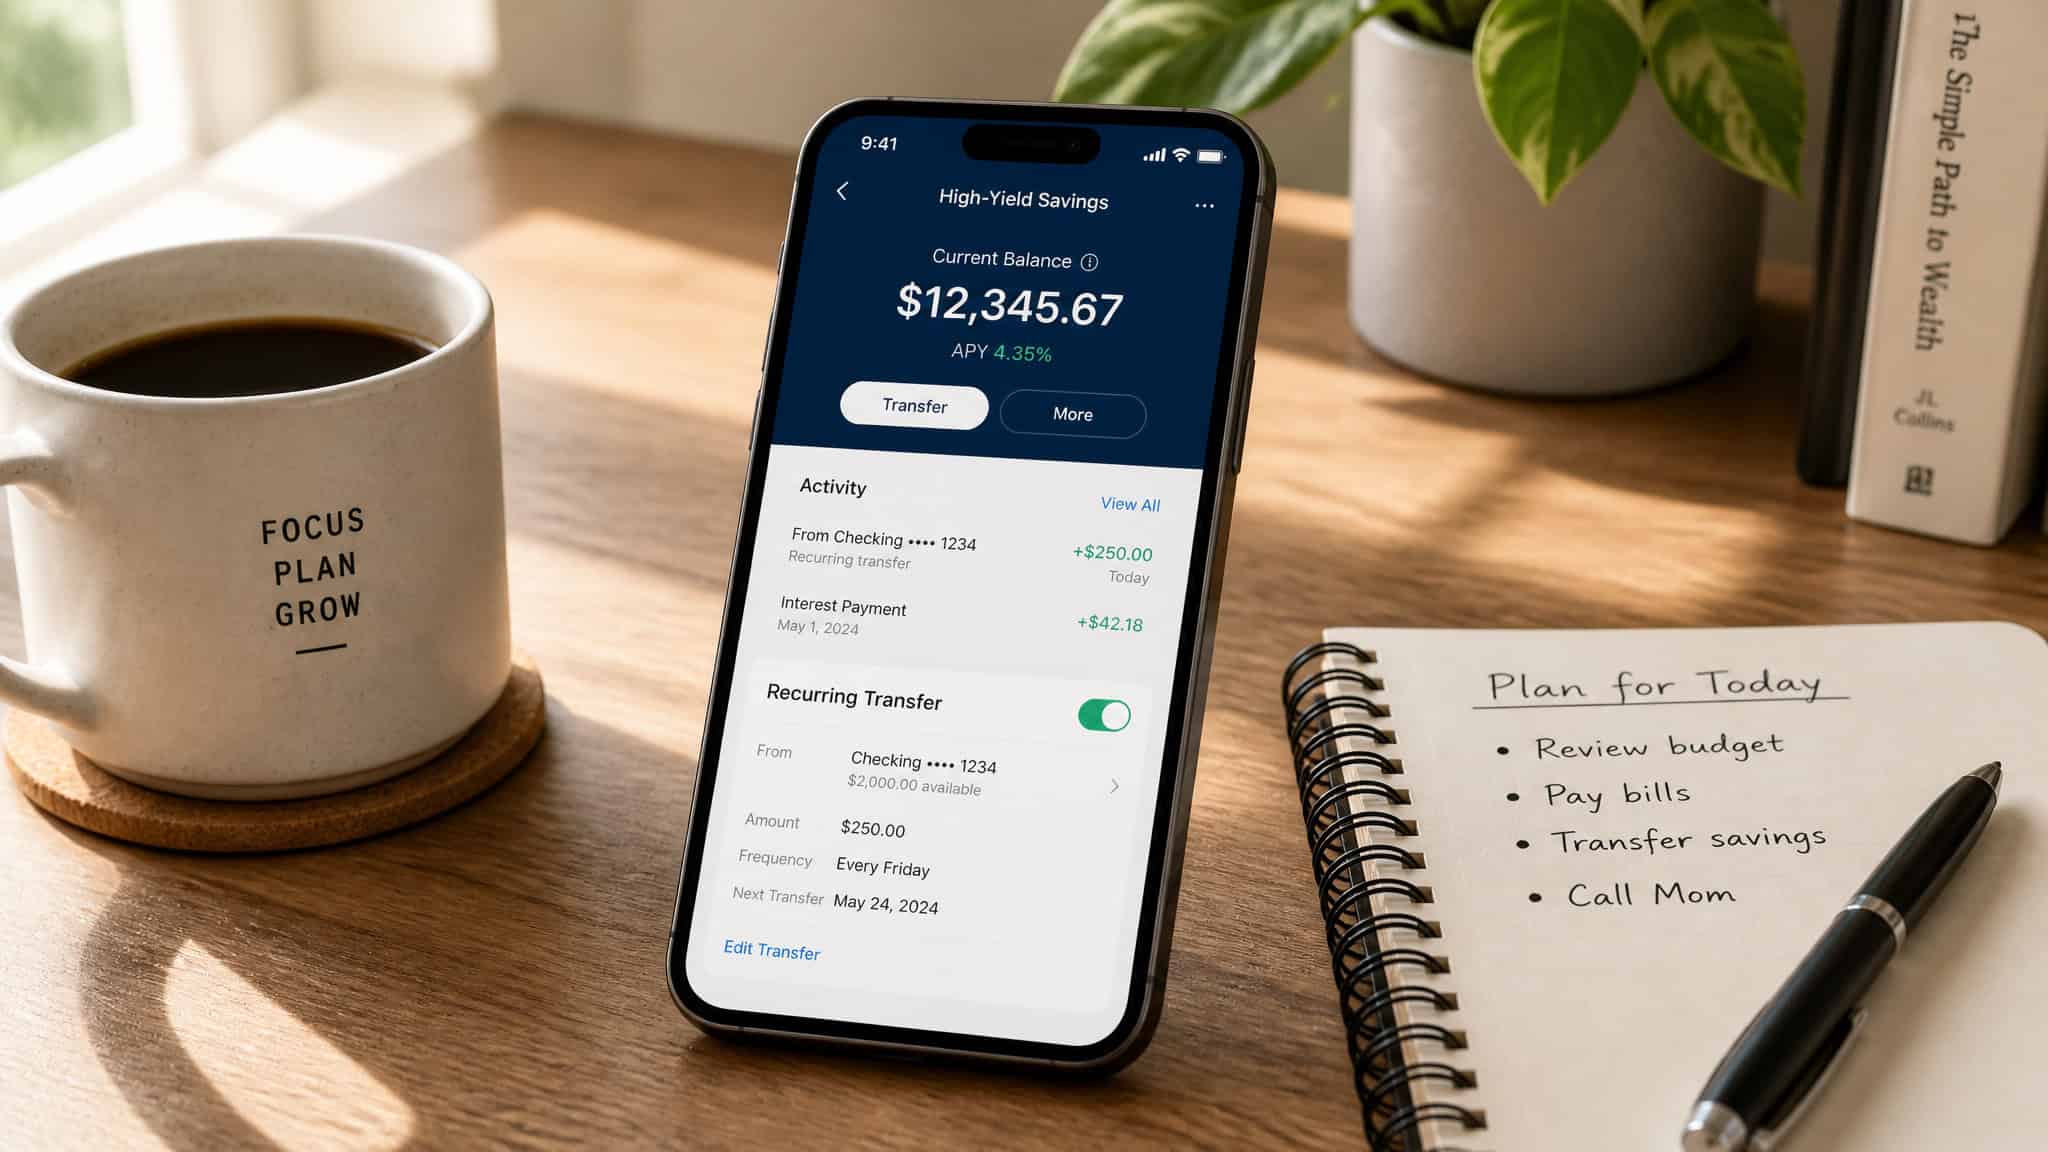
Open a Separate High-Yield Savings Account
Keep the repair money out of your checking account, or you’ll spend it. A separate high-yield savings account keeps it out of sight and earns a little interest while it waits. Think of this as your home emergency fund — the money you tap only when something breaks, not for upgrades or wants.
Calculate Your Monthly Transfer
Use 2% of the purchase price divided by 12 as your default. A $250,000 house means $5,000 a year, or $415 a month. Set up a recurring transfer that lands on payday, so the money moves before you can spend it.
If $415 a month isn’t realistic right now, don’t abandon the system. Start smaller and increase the transfer when you can.
Use Tax Refunds and Small Cuts to Boost the Fund
Coffee and takeout are the classic examples for a reason — cut a few a month and transfer the savings into the account. And when the tax refund hits, send it straight to maintenance. That’s a free $1,000-plus boost most guys blow on something else.
Start Small and Ramp Up
The set dollar amount method works when perfection is not possible. $50 to $200 a month genuinely is better than nothing, and it builds the habit. The goal is a funded account, not a perfect number on day one.
When Savings Aren’t Enough
If the fund comes up short and the bill can’t wait, you have options, but they’re fallbacks, not a plan. Before you borrow anything, check whether the dead appliance is still under warranty — many systems carry multi-year coverage, and assuming you’re out of luck is how people pay for things twice.
Home Warranty: A Supplement, Not a Replacement
A home warranty is a service contract covering repair or replacement of major systems — HVAC, appliances, electrical, and plumbing. You pay a yearly fee plus a service-call fee when something breaks. Plans typically run $500 to $800 a year.
It can be a decent safety net for an older house where things are more likely to fail, which is why first-time buyers often end up with one. But read the fine print: coverage caps and exclusions are real, and the FTC has warned consumers about how these contracts are sold. Treat a warranty as backup for savings, not a reason to skip them.
Home Equity Loans and HELOCs
Both let you borrow against the equity you’ve built. The upside is lower interest rates than personal loans or credit cards. The risk is the big one: your home is the collateral. If you can’t pay it back, you’re putting the house on the line.
Personal Loans: Flexible but Watch the Rates
A personal loan gives you a lump sum with fixed payments and no collateral. The catch is the rate — with a lower credit score, the interest can be brutal. Shop around before you commit.
Credit Cards: The Last Resort
Credit cards are the most expensive way to pay for a repair, so treat them as the last resort. The one workaround is a 0% APR introductory offer: if you can pay the balance off before the promo period ends, the card costs you nothing. If you can’t, the interest turns a small repair into long-term debt.
HOA Fees: Some Maintenance Is Already Paid For
If you’re in an HOA, part of your monthly fee covers maintenance you’d otherwise own. Landscaping, snow removal, and pest control for common areas and exteriors are the typical items. That doesn’t erase your personal maintenance budget — the stuff inside your walls is still yours, but it does shrink the exterior side of it.
The Cheapest Repair Is the One You Avoid
A furnace filter costs about $20 and takes five minutes to change. A new HVAC system runs $5,000 to $16,000. That’s the argument for preventative maintenance in two numbers.
Thumbtack’s Morgan Olsen calls it a safety net for your biggest asset. He’s right, but a safety net only works if you use it. Inspect and clean things every summer and fall, replace furnace filters, clean air vents, and test smoke alarms and CO detectors. And don’t wave off small leaks — that’s exactly how a $300 plumbing repair becomes a $4,000 damage claim. Thumbtack’s free personalized maintenance guides, available in the app, lay out what your specific house needs, which beats guessing.
Your Home Maintenance Budget in Practice
Here’s the version to keep in your head: budget 1% to 4% of your home’s value, or $1 per square foot as a quick shortcut, then adjust for three things — the age of the house, where it’s located, and the age of the major components. New construction in a low-risk area can often live at 1%. An older house, or one in a disaster-prone region, needs the full 2% to 4%.
Worked example: a 30-year-old, $350,000 house with the original roof. That’s $7,000 to $14,000 a year, or $580 to $1,167 a month, starting now rather than when the roof starts dripping. It sounds like a lot until you stack it against an $11,373 roof replacement and an $8,219 HVAC failure landing in the same year.
Calculate your number today, open a separate account, and set up the automatic transfer. Start with what you can afford, even if it’s $50 a month.
The exact percentage matters less than the habit — the guys who get blindsided aren’t the ones who undersaved by a few dollars. They’re the ones who never started.
Frequently Asked Questions
What is the most expensive thing to fix on a house?
The roof and HVAC system are the biggest budget-busters. A roof replacement runs $5,800 to $16,000, and an HVAC replacement costs $5,000 to $16,000, with the average roof repair bill landing at $11,373 and the average HVAC replacement at $8,219. These two can hit within a few years of each other, especially when a house is 15–20 years old.
What is the 1% rule for home maintenance?
The 1% rule says to save 1% of your home’s value each year for maintenance, but it’s actually a 1%–4% range. For a $200,000 house, that’s $2,000–$8,000 a year. The 1% figure is a floor, not a ceiling—newer homes can get away with it, but older homes or those in high-cost areas need 2%–4% to cover major repairs like roof and HVAC replacements.
What’s the difference between the 1% rule and the square footage rule?
The 1% rule uses a percentage of your home’s value (1%–4% per year), so it scales with market appreciation but gives a wide range. The square footage rule is simpler: $1 per square foot per year, so a 3,000-square-foot house needs $3,000 annually. The square footage rule ignores age, condition, and location, making it less effective for older or high-value homes, but it’s useful for quick mental math on newer construction.